Sunday, September 6, 2015

Correction or Bear Market?


We have always been firm believers that the stock market is a function of intrinsic value plus investor sentiment. According to our analysis the U.S. stock market appears overvalued on a fundamental basis, but using fundamental analysis as the sole source in determining shorter-term market behavior has not been a successful strategy in our opinion. If the efficient market hypothesis held true, then this wouldn’t be the case. The insertion of human behavior can keep a market fundamentally over or under-valued for quite some time. Determining near-term trends are important for portfolio management in that it assists in putting in place hedging and portfolio protection strategies to protect invested assets when the stock market gets choppy and volatile.   

Investor sentiment is a difficult thing to track and interpret. Investors tend to be a fickle bunch that will move in a herd-like fashion. When we have a “market correction” defined as a greater than 10% retreat from the market peak without a corresponding economic recession, that represents a behavioral move as opposed to a more significant “bear market”, a move of +20% retreat from the peak. A bear market is more a function of fundamental variables such as earnings deterioration and economic recessions. Unfortunately the stock market is the ultimate leading indicator and we as investors cannot distinguish between a correction or a bear market until after the fact. The best we can do is analyze the data presented to us, devise the most probable investment thesis and implement the appropriate investment actions, knowing that the investment thesis needs to be fluid and easily moldable to suit changes in the market data.

When going through my weekend readings, I came across several sentiment indicators that make the case that the bottom has been set. 

The sentiment case for the bottom.

On the blog site The Short Side of Long, the authors pointed to the Investor Intelligence Bullish survey. They write, “Investor Intelligence Survey has been around for many decades and it aims to track the mood and opinion of financial advisors and newsletter editors. Readings reported yesterday show that bullish advisors have now fallen below 30% for the first time since March 2009. Furthermore, this reading is two and half standard deviations below the mean. Historically, it is very rare to see bullish percentage fall below 30% in this indicator. If the [sic] closely observe the chart above, ver [sic] the last two decades bullish readings below 30% were seen during the October 2002, November 2008 and March 2009.”  


Additionally, Bank of America Merrill Lynch's proprietary Sell Side Consensus Indicator shows extreme negative sentiment that is usually present near market troughs. This indicator was highlighted in Business Insider where they opine, “One of the more popular metrics used by contrarians is Bank of America Merrill Lynch's proprietary "Sell Side Consensus Indicator," which measures bullishness and bearishness among professionals based on how they're recommending clients allocate stocks in their portfolios. When many of them recommend avoiding or staying underweight stocks, this is a reflection of bearishness. And, as a contrarian indicator, this is interpreted as a signal to buy.”


The confusing part of the analysis from BAML is that they recognize the sentiment levels as a contratian “buy” signal and expect the market to return +17% over the coming twelve months but are currently recommending to clients to significantly underweight stocks at 54% of the portfolio compared to a traditional long-term average of 60 – 65%.

In the same article they go on to quote Citi’s Tobias Levkovich and his “Panic/Euphoric Model” I have been a tremendous fan and follower of Mr. Levkovich and think his work is brilliant, so when he provides insight I tend to listen. The article states, “Citi's Tobias Levkovich was on Bloomberg TV Monday afternoon discussing Citi's proprietary "Panic/Euphoria Model," which is a model that factors in nine metrics like the NYSE short-interest ratio, margin debt, Nasdaq daily volume as % of NYSE volume, the put/call ratio, AAII bullishness data, and others. "Statistically, you’re talking about a 96% probability that markets are up 12 months later," Levkovich told Bloomberg's Alix Steel and Scarlett Fu. In a note to clients in August, he wrote that this level of panic has seen an average 12-month return is 17.5%.”


Similarly, “Barclays' Ian Scott also circulated a note to clients noting the collapse in sentiment as measured by the Investors' Intelligence survey.” Sentiment towards stocks is now firmly below average, with just 9% more bulls than bears," Scott wrote. "While we would be the first to acknowledge that sentiment does not have a “call” on the market before 2009, in the post Financial Crisis environment, it certainly has. Indeed, whenever the percentage of bulls has dropped below 9.5% the market has consistently been higher 6 months later, with an average gain of 22%."”


Another sentiment indicator we track is the AAII Investor Sentiment Survey. The latest reading shows of those participants surveyed, 32.4% are bullish on the market while 31.7% are bearish. I like to take a ratio of “bulls/bears” and come up with a current reading of 1.02. Typically a reading of 0.60 for lower is a sign of extreme bearishness and could be considered a buy signal. This ratio is considered to be quite low currently and indicative of a contrarian buy signal. The caveat here is that this ratio has been giving overly pessimistic readings from the start of the year so the contrarian quality of this model has not been all that accurate lately.


The latest Gallup Poll on economic confidence continues its descent. The latest reading indicates the following: “Americans' confidence in the economy continued to fall last week. Gallup's U.S. Economic Confidence Index slid three points to -17 after also declining three points the prior week. This is the lowest the index has been since September 2014, and comes as international markets struggle amid volatility in China's stock market.”


They conclude, “The plunge in China's stock market has caused repercussions far beyond Asia, sending financial markets worldwide into tailspins last week. In the U.S., combined losses of over 1,000 points in the Dow Jones industrial average have pushed Americans' economic confidence further into negative territory. Late last week, U.S. markets appeared to stabilize somewhat -- in part because of positive indicators of the strength of the domestic economy, including a much better than initially reported GDP growth rate for the second quarter. While the Dow still struggles amid uncertainty in Asia, Americans' economic confidence seems to be recovering.”

A post by Business Insider shows that global asset correlations are increasing indicating investors are selling across the board (graphic provided by Morgan Stanley). When asset correlations reach such extremes it usually indicates a near-term bottom according to analysis done by Citi.


The concept makes sense to me but when viewing the graphic provided, I don’t see any relevance especially in 2003 and 2009 that marked major market bottoms. I do think correlation is important in that negative investor sentiment spilling over from China can drive our markets lower (more on this later).

If there truly is blood in the streets and investors are running for the exits then one wouldn’t know it from the data released by BAML client cash flow data. In their latest release (via Business Insider): “According to Bank of America Merrill Lynch, the firm's equity clients moved money into stocks at the fastest pace since at least 2008 during a week that saw markets crater to start the week but ultimately finish in the green.”


“The firm's clients were net buyers of $5.6 billion of US stocks from August 24 to August 28. Though BAML noted that no single client group — which covers hedge funds, institutional investors, private investors, and corporations — saw a record flow relative to its own history.”

We believe that extreme negative investor sentiment is a precursor of market bottoms and the cash flow actions exhibited by BAML clients run counter to that. Perhaps there is a sense of security that the Fed will come in and launch measures to sustain equity prices. We have had several years to become accustomed to the “Fed put” providing a floor during market turmoil. Should the Fed not come to the rescue this time around things could take a turn for the worse and investor sentiment, along with the stock market may suffer.

In a note from Deutsche Bank (via Business Insider), “The note recaps the landmark moves of last week: a so-called seven-sigma move in equities, an all-time record change in the volatility of volatility, a 700-point change in the S&P 5oo over the week, and four consecutive days of six-sigma moves in oil. All in all, according to the note, "recent trading sessions were nothing short of extraordinary." The strategists took a look at similar historical periods to try and get a read on how markets typically react in the aftermath of such historic events. The Vix, which uses option prices to gauge expectations of volatility, closed above 30 three days in a row early last week, and did the same Tuesday. It is currently trading at around 26.”


“History seems to suggest that once volatility jumps to 30, it will stay there for several weeks, and in some cases months. That has been the case on seven different periods in the past, according to the note.

It said: The only exceptions that happened during the past 20 years have taken place in early 2000 and late 2007/early 2008. So technically speaking, even periods of quick reversal from a 30pt VIX levels have previously proven to be prescient indicators of more volatility to come down the road. We would thus caution our readers not to be too quick in dismissing what happened over the past two weeks as simple "overreaction".”

The September Effect

According to Money on-line, “Sam Stovall, U.S. equity strategist for S&P Capital IQ, points out that despite the market’s tremendous rebound last week, the S&P 500 index of blue chip U.S. stocks is still down 5.5% month to date. Why is that significant? “In the 11 times that the S&P 500 fell by more than 5% in August, it declined in 80% of the subsequent Septembers, and fell an average of nearly 4%,” Stovall says. Plus there’s the fact that the Septembers, like August, are one of the spookiest months for stocks. Over the past quarter century, August has been the worst month for the Dow and S&P 500. Yet over the past half century, September actually holds that title, according to the Stock Trader’s Almanac.”

We expect to see continued weakness in the market. While sentiment indicators appear to be bottoming and may provide a bounce higher from here, we will continue our cautionary stance until we can get further clarity on whether this is a correction that is winding down or the start of a bear market. With intermediate and longer-term momentum falling, we will use any short-term overbought situations to increase our portfolio protection or take a directional stance for our more opportunistic clients.


China

Continued weakness in China may increase negative investor sentiment in the U.S. markets. A survey done on the blog site Vix and More states the following: “In the chart below, I have summarized the top ten responses from almost 400 voters, covering 40 countries over the past two days.  The question:  “Which of the following makes you most fearful anxious or uncertain about the stock market?””


Weakened economic growth in China comes out on top. Indeed the economic data coming from China and the rest of the world (ex-U.S.) seems to be deteriorating.  Last week saw the official manufacturing PMI for China fall to 49.7 in August. This is the lowest reading since August 2012 and signifies manufacturing contraction in the country. The Caixin-Markit manufacturing slipped to 47.3, the steepest contraction since March 2009 and also suggests their manufacturing sector is shrinking. The decline in everything raw materials confirms this notion.

A sure tell-tale signal that China’s economy is slowing is the South Korean export figure for August. According to Business Insider, “South Korean exports in August plunged 14.7% from a year ago. This was much worse than the 5.9% decline expected by economists. And it was the biggest drop since August 2009. This is a troubling sign, as Korea's exports represent the world's imports. Because it is the first monthly set of hard economic numbers from a major economy, economists across Wall Street dub South Korean exports as the global economic "canary in the coal mine." Korea is a major producer of goods ranging from automobiles and petrochemicals to electronics such as PCs and mobile devices. "The country has long been a reliable bellwether," HSBC's Frederic Neumann told Reuters.”


“China, the world's second-largest economy, is Korea's biggest customer. And while many experts are skeptical of the reliability of China's official trade data, few doubt the quality of Korea's data. "In the last decade, China was a major growth driver for Korea," Morgan Stanley's Sharon Lam said on Tuesday. "Korean exporters are proud of their success in China, as witnessed by Korea overtaking Japan to become China's number one import source since 2013. Korea's success in the Chinese market was characterized by its brand name, technology, and marketing efforts. Unfortunately, China is no longer a positive factor for Korea and in fact it has become a negative drag."”

The International Monetary Fund has come out last week to reiterate their thoughts that the global economy is prone to slowing with the slowdown in China as a key culprit. Previously they called for the Fed to reconsider tightening monetary policy in the U.S. as the global outlook appears to be deteriorating. They cite the slowing Chinese economy, weakening commodity prices, strong U.S. dollar, emerging market struggles and market volatility as reasons for the Fed to stand down. Time will tell but the Fed appears to be on pace to raise rates sometime this year.

Just a glance at the global economic headlines last week paints a dour picture of current events.


·         US manufacturing is decelerating. The ISM manufacturing index fell to 51.1 in August from 52.7 in July. This was worse than the 52.5 forecast by economists, and it was the lowest reading since May 2013. 10 of 18 industries reported growth. From the ISM: "The New Orders Index registered 51.7 percent, a decrease of 4.8 percentage points from the reading of 56.5 percent in July. The Production Index registered 53.6 percent, 2.4 percentage points below the July reading of 56 percent. The Employment Index registered 51.2 percent, 1.5 percentage points below the July reading of 52.7 percent." – Business Insider

·         The eurozone manufacturing PMI slipped to 52.3 in August from 52.5 in July. Italy, Spain, Ireland, Netherlands, and Austria all experienced deterioration in growth. Meanwhile, France's PMI fell to a four-month low of 48.3, which reflects outright contraction. – Business Insider

·         Canada is in recession. GDP contracted at a 0.5% rate in Q2 following a 0.8% contraction in Q1. The back-to-back quarters of contraction mean that the economy is in recession. – Business Insider

·         Macau gaming revenue crashed. Gaming revenue in Macau crashed 35.5% in August, marking a 15th straight monthly decline, according to the FT. The pronounced slowdown comes after Beijing's crackdown on VIP gaming, but weakness can also be seen in the "mass" revenue data. On Monday, Macau announced second-quarter gross domestic product collapsed 26% compared with last year. – Business Insider

·         French Manufacturing continues to reel. France's Final Manufacturing PMI fell to 48.3 in August, from 48.6 in July. The number was shy of the 48.6 that economists were forecasting and makes for the worst reading in four months. Italy and Spain also saw slowdowns in manufacturing while Germany's reading climbed to 53.3, its best level since May 2014. The eurozone as a whole saw its reading slip to 52.3 from 52.4. The euro is stronger by 0.5% at 1.1267. – Business Insider

·         Reflective of weakness in China and the US, growth in global manufacturing activity decelerated sharply in August with the J.P. Morgan-Markit global manufacturing PMI gauge falling to 50.7. While activity has expanded for 33 consecutive months, the reading was the lowest seen since April 2013. – Business Insider


With the seemingly slowing economic profile, does that mean the U.S. will catch the contagion of the global slowdown? For us it’s way too early to know but Scott Grannis from Calafia Beach Pundit agrues against that scenario. He writes, “Markets are still on edge, worried that a China slowdown will prove contagious to the rest of the world—a new twist on the old catchphrase "When the US sneezes, the rest of the world catches a cold." But the mainstay of the U.S. economy—the service sector—is still quite healthy. The U.S. economy has been underperforming for years, but that has everything to do with our own bad policy choices. Even a substantial slowdown of the Chinese economy would have little impact on the U.S., since China's purchases of goods and services from us represent a mere 0.7% of our annual GDP.”


“As the chart above shows, the service sectors of both the U.S. and the Eurozone have been gradually improving over the past year or two (and the U.S. survey beat expectations, 59 vs. 58.2). This arguably trumps any slowdown in the growth of the Chinese economy.”


“The Business Activity subindex of the ISM service sector survey is still at historically high levels, and doing much better than at anytime during the current expansion. This represents about 80% of our GDP. This is great news.”


“The Employment portion of the ISM service sector survey is still at relatively healthy levels. This suggests that businesses are reasonably confident about their future prospects.”

Bottom Line: There is no way of determining if this is going to be a market correction in the bull market or the start of a new bear market. Thus far the evidence points to a correction thesis as we believe it would take a U.S. economic recession to materialize to initiate the bear market case. We expect continued market volatility with a near-term rally followed by market weakness into the end of 3Q and into 4Q before stabilizing and heading higher again. Intermediate and long-term momentum remains negative and we will be preparing to use overbought situations to protect and/or monetize further weakness. Should the global and U.S. economic picture continue to deteriorate, then we will readdress our thesis.

Joseph S. Kalinowski, CFA


Additional Reading


Rising Anxiety That Stocks Are Overpriced – Robert Shiller oped New York Times


No part of this report may be reproduced in any manner without the expressed written permission of Squared Concept Partners, LLC.  Any information presented in this report is for informational purposes only.  All opinions expressed in this report are subject to change without notice.  Squared Concept Partners, LLC is an independent asset management and consulting company. These entities may have had in the past or may have in the present or future long or short positions, or own options on the companies discussed.  In some cases, these positions may have been established prior to the writing of the particular report. 

The above information should not be construed as a solicitation to buy or sell the securities discussed herein.  The publisher of this report cannot verify the accuracy of this information.  The owners of Squared Concept Partners, LLC and its affiliated companies may also be conducting trades based on the firm’s research ideas.  They also may hold positions contrary to the ideas presented in the research as market conditions may warrant. 

This analysis should not be considered investment advice and may not be suitable for the readers’ portfolio. This analysis has been written without consideration to the readers’ risk and return profile nor has the readers’ liquidity needs, time horizon, tax circumstances or unique preferences been taken into account. Any purchase or sale activity in any securities or other instrument should be based upon the readers’ own analysis and conclusions. Past performance is not indicative of future results.


Monday, August 31, 2015

We Expect Additional Market Weakness Going Forward


The market bounced off the lows from last Monday and offered a trading opportunity for those aggressive traders that chose to capitalize on the recent volatility. As of this writing at 1 am Monday morning, it appears the Asian markets are trading lower and U.S. futures are indicating a lower open. Last week we wrote that we expected a near-term bounce but expected the market to continue lower. We believe the technical damage to the market over the past several days is fairly severe. Investor sentiment may be turning increasingly negative, momentum is weak and the markets remain overvalued in our opinion. We believe it is possible for the S&P 500 to retest the lows from last year at around $1820 over the next several months. We will trade the market to the downside by shorting over-bought situations until there is improvement in the sentiment/momentum picture.  


The Next Bear Market

There has been a significant amount of discussion on whether this is a classic correction (+10% stock market decline) or the start of something more sinister. The accepted definition of a “bear-market” is a +20% decline from the peak of a specific index. I came across this interesting piece from JP Morgan (Via Business Insider) that profiled the start of historical bear markets. The article states, “JP Morgan's review of global markets and economies included a look back at the past ten bear markets in US history, dating back to the Great Depression. To qualify, S&P 500 had to drop 20% off the all-time high. Looking at the slide, there are some themes that pop out. Maybe most obviously, 8 of the 10 were accompanied by recessions as defined by the National Bureau of Economic Research. The three main hallmarks JP Morgan observed — commodity spikes, aggressive Fed tightening and extreme valuations — each occurred four times over the 10 bear markets and only once, the 1987 crash, bore none of those hallmarks. Commodity spikes (defined as "significant rapid upward move in oil prices") and aggressive Fed tightening ("monetary tightening that was unexpected and significant in magnitude") occurred together 3 times and is what JP Morgan cites as conditions during the 2007 Global Financial Crisis. While it may simplify broad economic situations, the chart provides an intriguing snapshot of when and why US markets meltdown.”


We firmly believe, based on the data that we currently have that this is a market correction and not the start of a new bear market. The leading economic indicators that we track are showing slow but stable growth, so it doesn’t appear an economic recession is on the horizon. The Fed is going to start a tightening cycle but given the ultra-easy monetary policy in place, a small increase in rates doesn’t appear to be a threat to the market. Commodities are not spiking, in fact quite the contrary the sector has been chronically weak.  

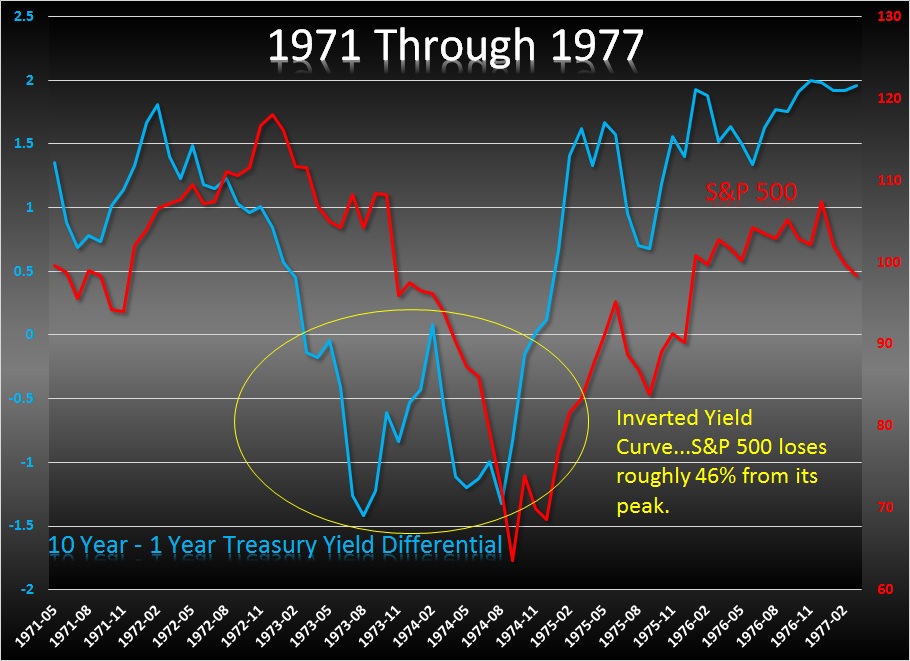
Perhaps the most important item we track is the yield curve. Typically the yield curve will become inverted when economic growth is threatened and the stock market is weakened. I have listed previous points in history when the yield curve had become inverted and subsequent market under performance. The last chart of this series shows where we are today and quite frankly it doesn’t appear to be a major threat signifying a bear market – yet. We’ll be watching closely.


Bottom Line: We expect additional market weakness once this market bounce concludes, possibly through September and October. We may see the S&P 500 retest the levels hit in October of last year. We would like to see valuations come in line and sentiment improve and are hopeful of a renewed rally as we head into the end of the year. Given the current data, we do not see this turning into a severe bear market but will be watching the data closely.

Joseph S. Kalinowski, CFA


Additional Reading:

Does stock market decline signal a recession? – The San Diego Union-Tribune

This is 'the danger' – Business Insider


No part of this report may be reproduced in any manner without the expressed written permission of Squared Concept Partners, LLC.  Any information presented in this report is for informational purposes only.  All opinions expressed in this report are subject to change without notice.  Squared Concept Partners, LLC is an independent asset management and consulting company. These entities may have had in the past or may have in the present or future long or short positions, or own options on the companies discussed.  In some cases, these positions may have been established prior to the writing of the particular report. 
The above information should not be construed as a solicitation to buy or sell the securities discussed herein.  The publisher of this report cannot verify the accuracy of this information.  The owners of Squared Concept Partners, LLC and its affiliated companies may also be conducting trades based on the firm’s research ideas.  They also may hold positions contrary to the ideas presented in the research as market conditions may warrant. 
This analysis should not be considered investment advice and may not be suitable for the readers’ portfolio. This analysis has been written without consideration to the readers’ risk and return profile nor has the readers’ liquidity needs, time horizon, tax circumstances or unique preferences been taken into account. Any purchase or sale activity in any securities or other instrument should be based upon the readers’ own analysis and conclusions. Past performance is not indicative of future results.


Sunday, August 23, 2015

How We Position Ourselves From Here


It’s been quite a week for investors as sentiment has decidedly turned negative. The trick is not to panic. Two weeks ago we decided to add portfolio protection in our program portfolios. We wrote in our blog on August 9th entitled Time to Consider Portfolio Protection, “Market fundamentals are signaling over-valuation and market sentiment/momentum appears to be weakening. This along with less accommodative monetary policy on the horizon increases the risk of a market correction, in our view. We will maintain our existing portfolio but will start introducing “portfolio insurance” in the coming weeks and months as the market dictates. It is impossible to predict market tops and bottoms but it is prudent to alter the risk profile of the portfolio with changes in market data. We’d rather risk a portion of future upside if we are wrong in our analysis than risk previous gains if we’re right.”

We are fortunate to not have suffered major losses in our program portfolios and our more opportunistic portfolio is decidedly positive month-to-date. Given the recent action, it’s now time to review our positions and continue to build upon our investment thesis.

Short-term Action

We are expecting the market to stage some sort of rebound from its current level. In the figure below, we are seeing what I would describe as fairly rare opportunities. On Friday, the spot and future prices for the VIX inverted and that ratio shot above one. This usually signifies a near-term market bottom. The Put – Call ratio spiked to 1.69. Anything above 1.4 also indicates near-term overreaction and a possible bounce in the market. Lastly, the VIX itself rallied over 100% in the past five trading days. When looking at the second derivative rate of change for the VIX, anytime there is a big upward spike in such a time frame, it usually indicates a near-term buying opportunity. In fact, going back to 1990 there have only been 31 cases in which the VIX spiked over 50% in five trading days. In 27 of those cases (87% of the time) the market traded higher over the next five trading days with an average gain of 3%.


Staying with the S&P 500 as a benchmark, both the RSI (5) and fast stochastics are signaling extreme oversold conditions. We would expect the market to rally to the top of the shaded range in the following figure or roughly 2020. Depending on the strength of the rebound we may see the market advance further to 2040 which appears to be the base of the neckline that started earlier this year. Beyond that the next resistance level may be the 200-day moving average of 2077 but I’m doubtful that level will be reached given the severity, volume and technical damage of this sell-off. We will see how trading next week starts and if we see stabilization and upward action on the daily MACD histogram, we will take profits on the equity put options that we introduced to the portfolio. For our more opportunistic clients, we will be looking to trade the bounce.


Intermediate – Term Action

That said, weekly and monthly momentum is decidedly negative for the SPX and portfolio insurance is a fact of life for the foreseeable future. We believe the stock market will continue lower after the short-term bounce described earlier. We will be looking for a few things. We would want to see (1) the RSI (5) and fast stochastics reach overbought levels, (2) one of the three test points mentioned earlier provide verifiable resistance and (3) daily MACD histogram resume lower. If those events were to happen, we will reposition ourselves with the appropriate downside protection and look for additional market weakness.

We have written in the past that fundamentally it appears the market is overvalued and is due for a correction. (See  The Coming Market Correction?)    We did not know what the catalyst would be to start the correction as investor sentiment remained bullish. We commented that a possible cause of the coming correction may be unsettling headlines out of China. It appears that may be happening. An article in CNN Money entitled - China's economy is in trouble. How bad is it? ; states two sides of an argument. They write, “There is almost no way that China's economy is growing as well as the government says it is. For years, experts have questioned whether China cooks its books. "The question is not whether they're right, it's how wrong are they," says Derek Scissors, an Asia expert at the American Enterprise Institute.  But you don't need a PhD in statistics to figure it out this time. Just take a look at what China's government has been doing lately: making a surprise devaluation of the yuan in an effort to boost exports, propping up its markets by actually buying stocks, spending big and cutting interest rates in an effort to stimulate its economy. China wouldn't be taking these actions if the country really was chugging along at the 7% growth rate that the latest government data claims. "China could be in the world's greatest depression and they would still report 7%," says Gordon Chang, a China expert and author of “The Coming Collapse of China." (Emphasis added)

They go on to compare two popular arguments on the Chinese economy:

“Here's the case for a 2% vs. 5% growth scenario:

1. It's a major slowdown. Chang says he has heard that in Beijing, they are privately talking about 2% growth. He's not surprised. Across the board, the statistics don't look good with everything from steel to rail freight to electricity consumption showing big drops. China's manufacturing sector looks especially weak -- sentiment just hit its lowest level in six years.

"There's a lot there that looks really wrong," says Chang.

While Chang acknowledges that China is taking various stimulus measures, he is concerned that a lot of the growth is coming from people, companies, real estate developers and even local governments taking on more debt. "The growth they are creating is crap growth," says Chang. "They're aggravating their debt problem and they have no solution." He estimates the true GDP number is likely 1% to 2% growth. Expect China to hurt American company earnings for the rest of the year. Even worse, expect more panic "because people think that China is more important than it actually is."”

Or…

“2. It's a minor hiccup. Other experts say that predictions of a "hard landing" in China go too far.

"This is not 2009," says Scissors, the America Enterprise Institute scholar. He estimates GDP is growing at about 4.5%. Global forecasting company Capital Economics has traded jabs with the Chinese government before over the validity of the government statistics. Capital Economics believes China is likely growing at 5% to 6%. China's economy probably did a lot worse than what it reported in the first half of the year, but there could be a pickup in the second half, especially as all of the stimulus measures take root. "There are signs the economic conditions are improving," says Mark Williams, chief Asia economist at Capital Economics. He reminds people that growing at 5% to 6% isn't the "very dark place" some are warning about. Another key for Americans to remember is that when the Chinese get nervous, they tend to invest their money abroad. "Bad Chinese economy performance means more Chinese money leaving their country, and the No. 1 place it comes is here," says Scissors.”

What stands out to me is that the argument has shifted from a “grow vs. slow” debate to “slow vs. even slower” one. A slowing Chinese economy certainly has profound implications on our economy and equity markets but it’s yet too soon to know if this will result in a U.S. market correction or the groundwork for the next “big – one” bear market.

This turmoil is definitely reflected in asset prices in Asia. According to Arthur Hill at StockCharts.com, “SHANGHAI COMPOSITE BREAKS LONG-TERM MOVING AVERAGE... Chart 11 shows the Shanghai Composite ($SSEC) moving below its 50-day moving average, stalling and then breaking its 200-day moving average. A triangle formed to mark the consolidation over the last two months and this is a consolidation within a downtrend, which is typically a bearish continuation pattern. With a close at 3507 on Friday, the index broke the 200-day and triangle support to signal a continuation lower. Chart 12 shows the X-Trackers China A-Shares ETF (ASHR) breaking support in late June, bouncing back to 44 and breaking down again this week.”


For the purposes of our intermediate investment strategy we will assume recent market action as the start of a potential market correction (down 10% from its peak) vs. a bear market (down 20%). A keen eye on portfolio protection and defending previous gains is warranted as we wait and see if investor sentiment has truly taken a turn for the worse.

Speaking of Investor Sentiment

In an interview with CNBC, Robert Shiller stated the following on the contagious effects of negative investor sentiment. They write,”Nobel Prize-winning economist Robert Shiller has warned for months against being overexposed in an overheated market. And with the major U.S. averages pacing to cap their worst week of the year Friday, it certainly appears to be a well-timed caution, but Shiller isn't saying it's over yet. "It could be followed by even bigger and bigger moves," he told CNBC's "Squawk on the Street" in an interview. "I have a general bias towards down because the market is overpriced, but these things unfold over years." While Shiller conceded the possibility that the selloff could "create aftershocks in either direction in the short-term," he highlighted a psychological bias for those in the periphery to "over focus on the latest news." "When people who don't normally pay attention to the market are brought in, it can feed on itself like an epidemic," he said.”

The Case for a Correction

Negative headlines out of China and the potential of investor pessimism spreading has us looking at fundamental valuation once again. Several weeks ago we wrote, “Based on Bloomberg data, the companies that comprise of the S&P 500 are expected to show $125.71 in earnings per share over the coming twelve months and have a current earnings yield of 6.1%. Book value per share for the index is $736.68 with a BV yield of 35.4% and cash flow per share of $180.23 for a CF yield of 8.8%. If we weight each valuation measure according to accuracy in predicting future price movements our blended fair value for the S&P 500 is $1702 or about 18% overvalued.”


We are of the opinion that the combination of negative news, deteriorating investor sentiment and an overvalued market could be the genesis of a +10% correction for the S&P 500. Other valuation measures outside of our own paint a similar picture.

Henry Blodget, of Business Insider writes this, “In the past year or two, stocks have moved from being "expensive" to being "very expensive." In fact, according to several historically valid measures, stocks are now more expensive than they have been at any time in the past 130 years, with the exception of 1929 and 2000 (and we know what happened in those years). The chart below is from Yale professor Robert Shiller. It shows the cyclically adjusted price-earnings ratio of the S&P 500 for the past 130 years. As you can see, today's PE ratio of at least 26 is miles above the long-term average of 15. In fact, it is higher than at any point in the 20th century, with the exception of the months that preceded the two biggest stock-market crashes.”


“What about other valuation measures? Most of them paint the same picture. Here, for example, are a few recent charts from Doug Short, one of the best market-chart makers around. The first chart plots four valuation measures — the Shiller P/E ratio above, another P/E ratio (different calculation), the "Q ratio" (a measure of price to replacement cost), and a regression analysis for stocks themselves. Same message: Averaging the four suggests that stocks are ~80% overvalued.”


“And for good measure, here's another ratio — one that is fondly referred to as "Warren Buffett's favorite valuation measure." (Because he once said it was.) This one charts the collective value of all stocks to the size of the economy (GDP). It recently hit its second-highest level ever.”


More Evidence of Intermediate Market Weakness – Credit Spreads

As this article in Fox Business reports, “With the S&P 500 and the Dow Jones Industrials tossing away their gains for the year, bond prices are rising in what could be a bad omen for U.S. stocks. Investors poured $1.3 billion into U.S. Treasuries for the week ended August 19, the biggest score since mid-April, according to data from Thomson Reuters’ Lipper. The yield on the 10-year benchmark, which trades inverse to bond prices, is hovering at 2.084% and has been on the decline since early July; and that trend may continue according to Mary Ann Bartels, chief investment officer of portfolio solutions at Bank of America Merrill Lynch Wealth Management (BAC). “The 10-year yield is starting to break down, technically pointing to lower lows, it could break 2% technically,” said Bartels on FOX Business Network’s Mornings with Maria.” 

“As bond yields fall and bond prices rise, U.S. stocks are paying the price. As of Thursday, the S&P 500 is down 1% for the year, the Dow Jones Industrials nearly 5% while the Nasdaq Composite hangs onto its 3% gain. A big reason investors are gravitating toward the safety of U.S. government debt is China. “Large institutions are selling due to China.” said Jason Rotman, managing partner of Lido Isle Advisors, while appearing on FOX Business Network’s Risk & Reward.”

The standing divergence between credit spreads and stock prices has been pointed out previously in this blog as the bond market has been predicting a market correction from earlier this year. It is only now that the stock market seems to be listening to the warnings from the bond market.


Negative Intermediate – Term Momentum

The following graphic shows that long – term momentum has turned negative, solidifying our belief that the stock market will continue its downward move after the coming “bounce”. After a slight upward movement in the SPX to the 2020 - 2070 level the market should offer additional shorting – portfolio protection opportunities probably through September and October, in our opinion.


Is this the Big One?

The question will arise as to the magnitude of the continuation of the sell-off. We do believe a market correction (down +10% from the peak) is in order. We are not thinking a full blown bear market (down +20% from the peak) is in the cards. Of course this is nearly impossible to predict but our opinion is that all the intermediate problems mentioned above (negative news out of China, overvaluation concerns and deteriorating momentum) will wash out and the bull market will continue higher. We are anticipating a correction within the bull market currently.

We just don’t see the signals that we are accustomed to prior to a major downward movement in the stock market.

As Scott Grannis of Calafia Beach Pundit points out, “For the past several months, TIPS have been telling us that inflation expectations have been declining—though only moderately: deflation is still nowhere to be found. At the same time, the rise in real yields on TIPS tells us that the market is expecting somewhat stronger growth—though still far less than enough to erase the economy's huge output gap, which I estimate to be about $1 trillion per year. It's a message that should do nothing to derail the Fed's plan to normalize interest rates at a somewhat higher level, and it should do nothing to provoke an outright tightening of policy. Slow and relatively stable growth, accompanied by relatively low inflation, is not very exciting, but it's not something to worry about either. It's supportive of continued, modest gains in equity prices.”


“In the chart above, the difference between the nominal yield on 5-yr Treasuries and the real yield on 5-yr TIPS gives us an expected annual (CPI) inflation rate of 1.27% over the next 5 years. This is relatively low compared to past history for this series, but it is nowhere near the levels that reflect deflation risk, such as we saw at the end of 2008.”


“As the chart above shows, the recent decline in this same expected inflation rate over the next 5 years is driven by and large by the price of oil. Lower expected inflation is not a symptom of tight money; it is the by-product of strong gains in oil production. As such, this is a welcome development, since a lower cost of energy enables a stronger economy.”


“As the chart above suggests, the real yield on 5-yr TIPS tends to track the economy's growth rate. Which makes sense, since the real growth of the economy sets an upper limit on the real growth of its constituent parts. If the bond market is comfortable with risk-free real yields of 0.3% for the next 5 years, then real growth in the broad economy is quite likely to be somewhat higher. This year's increase in real yields suggests that the market is pricing in a modest acceleration in the rate of GDP growth over the next year or so. Nothing to get excited about, but nothing to worry about either.”

I like to track trucking and rail shipments as a gauge of economic activity. As we mentioned in our posting on July 12, we are still seeing year-over-year growth in rail traffic, although the numbers we track are provided quarterly so we will need to update this when the September figures are released. Truck tonnage continues to show gains as well. Back to the post by Scott Grannis, “The physical weight of stuff carried by the nation's trucks increased 3.7% in the year ending July. This is a pretty good indication that the economy is growing. As the chart [below] shows, truck tonnage correlates reasonably well with the real value of U.S. equities. As the economy expands, real stock prices increase, which makes sense. The modest increase in truck tonnage in the past years suggests that the stock market is not in a bubble (neither undervalued nor overvalued), and is likely to increase modestly for the foreseeable future.”


The Atlanta Fed publishes its GDPNow indicator that attempts to forecast quarterly economic growth. They have been very accurate of late and it is something I have started watching on a continuing basis. They write, “The GDPNow model forecast for real GDP growth (seasonally adjusted annual rate) in the third quarter of 2015 is 1.3 percent on August 18, up from 0.7 percent on August 13. The forecast for real GDP growth increased from 0.7 percent to 1.2 percent after Friday's industrial production release from the Federal Reserve. Most of this increase was due to a 15.3 percent increase in seasonally adjusted motor vehicle assemblies in July that boosted the forecast of the contribution of real inventory investment to third-quarter GDP growth from -2.2 percentage points to -1.8 percentage points.”


The housing market remains firm as well. According to Tom Lee of Fundstrat (via Business Insider): “The US housing market recovery is the most important reason to still believe in the bull market, according to Fundstrat's Tom Lee.”

“In a note to clients on Friday, Lee wrote (emphasis and link added): "In our view, the most important element for remaining constructive is the ecosystem benefiting from a US housing recovery. July 2015 housing starts rose to 1.206mm, reaching a 7-year high and further confirmation of a broadening housing recovery which should lead to US housing starts rising to 1.7-2.0mm (typical peaks) ... US residential construction is 3.3% of GDP but is expected to rise to at least 5.5% (1.7mm starts) and such an increase would more than offset the 40% decline in Energy capex, which has fallen from 1% of GDP to 0.6%. In fact, as we show, starts need to reach 1.374mm to fully offset the 40% decline in Energy spending, which could be seen within 12 months." Lee says that although the past few weeks have been the worst of 2015 for the stock market, his call for a longer-term rally, and the 2,325 year-end target on the S&P 500, is unchanged.”

Manufacturing continues to chug along despite weakening figures of late. According to Markit Economics, “U.S. manufacturers indicated a renewed loss of momentum during August, with output, new business and payroll numbers all increasing at a slower rate than in the previous month. As a result, the headline seasonally adjusted Markit Flash U.S. Manufacturing Purchasing Managers’ Index™ (PMI™)1 dipped from 53.8 in July to 52.9 in August. The index remained above the neutral 50.0 threshold, but the latest reading was the lowest since October 2013.”

The way I track manufacturing data is to combine all the surveys into one z-score that is easy to read and quick to reference. The aggregate manufacturing score combines ISM Manufacturing PMI, the Philly Fed outlook, the Dallas Fed manufacturing survey, the Chicago Fed activity index, the Empire State manufacturing survey, the Richmond Fed manufacturing survey and the Cincinnati PMI. I think that just about covers this country’s manufacturing sector. Outside of a strange divergence between the manufacturing figures and the S&P 500 that started earlier this year (possibly correcting itself currently) it appears the manufacturing sector continues to chug along as we have seen for many quarters with no significant breakdowns showing. Of course the market is the leading indicator in this case but further significant weakness in this model would change our investment thesis as it relates to a coming bear market.


Indeed many other economic metrics that we track are showing slow but positive year-over-year growth. Further deterioration in these economic models may sway our longer-term investment thesis but for now we are going to assume the economy is not heading for a recession.


Monetary Policy

We understand the Fed’s desire to normalize monetary policy and ween the market off of its multi-year ZIRP program. We watch the yield curve (the spread between the two and ten year treasury yield) as our best gauge of economic strength. An inverted yield curve is a dangerous sign for the stock market and we were not all that concerned about the current positioning until recently. The flight to quality is now driving the ten year yields lower just as the Fed anticipates raising rates on the short end. If the model below gets to an inverted position then we would definitely need to rethink our investment thesis but for the most part it currently is not flashing a long-term economic warning.


Given the recent market weakness, many are speculating that a Fed rate hike in September is off the table. From Business Insider, “On Wednesday, we got the much-anticipated minutes from the Federal Open Market Committee's July meeting. However, they did little to support anybody's conviction about a September rate hike. The minutes indicated that although the Fed saw the economy approaching the conditions appropriate for a rate hike, members thought those criteria had not yet been reached. From the minutes:

... The Committee agreed to continue to monitor inflation developments closely, with almost all members indicating that they would need to see more evidence that economic growth was sufficiently strong and labor markets conditions had firmed enough for them to feel reasonably confident that inflation would return to the Committee's longer-run objective over the medium term.

The Committee concluded that, although it had seen further progress, the economic conditions warranting an increase in the target range for the federal funds rate had not yet been met. Members generally agreed that additional information on the outlook would be necessary before deciding to implement an increase in the target range ...

And so, it seemed that the Fed simply confirmed what everyone knew — that the economy was accelerating — but not quite as fast as necessary to raise rates. At the end of the day, markets were left "slightly lost, upset, and confused," as Deutsche Bank's Jim Reid put it in a note to clients on Thursday. And this was enough to squash expectations for September. The probability of a rate increase next month plunged from 50% to 36% in a single afternoon on Wednesday.

And then, stocks entered a correction

In two days, US stocks tumbled far enough to log the worst week since September 2011. After falling to a six-month low on Thursday, the Dow on Friday lost more than 500 points and entered into a correction — defined as a 10% drop from recent highs. The S&P 500 closed down 5% for the week and lost more than 100 points in a week for the first time since 2008. On Friday afternoon, the probability for a rate hike next month was lower still, at 34%.”


Corporate Earnings

True revenues and earnings are slowing somewhat but we do not anticipate a severe earnings drought in the near-term. In our July 12th comments we wrote, “…it’s also beneficial to look at the quality of earnings that are produced within the S&P 500. I like to track the index net operating income less its cash flow from operating and investing activities. One can then scale it by total index assets for easier cross index comparisons but for simplicity the chart below is shown as a z-score or where it lies on the bell curve. Knowing how much of reported earnings is supported by cash received versus accrued is key when using financial ratios and attaching a multiple to determine fair value.

When the earnings quality line is falling, then earnings quality is deteriorating. When it’s rising then it an earnings quality improvement. Notice both the market tops in 1999 - 2000 and 2007 – 2008 correlated with a -4 reading in the EQ chart. While earnings quality currently is deteriorating, it is nowhere near the dangerous levels of the previous two bear markets. For all the talk about sinister financial engineering used to goose profits, it appears to me that there is still some wiggle room to continue down this road for a while longer.”


Bottom Line: In the near-term we are expecting the market to bounce from current depressed levels. We will use this opportunity to book profits from our protective positions and trade the bounce for our more opportunistic clients. Once the bounce has happened we will reinstate the portfolio protection as we believe the market will remain weak in the intermediate-term with a possible correction looming (+10% from the peak). This could last through October. For the long-term we believe this is a correction in a bull market and the economy and the market will resume its uptrend. We will make portfolio adjustments as the data dictates.

Joseph S. Kalinowski, CFA


Additional Reading


No part of this report may be reproduced in any manner without the expressed written permission of Squared Concept Partners, LLC.  Any information presented in this report is for informational purposes only.  All opinions expressed in this report are subject to change without notice.  Squared Concept Partners, LLC is an independent asset management and consulting company. These entities may have had in the past or may have in the present or future long or short positions, or own options on the companies discussed.  In some cases, these positions may have been established prior to the writing of the particular report. 

The above information should not be construed as a solicitation to buy or sell the securities discussed herein.  The publisher of this report cannot verify the accuracy of this information.  The owners of Squared Concept Partners, LLC and its affiliated companies may also be conducting trades based on the firm’s research ideas.  They also may hold positions contrary to the ideas presented in the research as market conditions may warrant. 

This analysis should not be considered investment advice and may not be suitable for the readers’ portfolio. This analysis has been written without consideration to the readers’ risk and return profile nor has the readers’ liquidity needs, time horizon, tax circumstances or unique preferences been taken into account. Any purchase or sale activity in any securities or other instrument should be based upon the readers’ own analysis and conclusions. Past performance is not indicative of future results.